Australia’s pubs and clubs are facing another cost-of-doing-business challenge following the removal of card payment surcharges, with concerns that promised savings for consumers could instead mean higher prices, new ordering fees and further pressure on venue margins.
The changes, effective from 1 October, prevent businesses from adding surcharges to most card transactions. But while the surcharge has disappeared from the customer’s bill, the cost of accepting electronic payments has not.
For publicans and club operators already managing rising wages, energy bills, insurance, food costs and government charges, the reforms create another decision: absorb the expense or pass it on through higher prices.
The Reserve Bank of Australia has indicated that payment processing costs can be incorporated into overall pricing. While this may simplify the checkout experience, it does not guarantee savings for patrons.
Beer, counter meals and coffee could all become more expensive as venues adjust prices to cover card acceptance costs. Customers who previously paid cash may also end up subsidising the transaction costs associated with premium credit cards offering rewards points and frequent flyer benefits.
Clubs Australia had warned in January 2026 that smaller clubs, with less bargaining power over merchant fees, would be disproportionately affected by a surcharge ban.
It advocated banning debit-card surcharges while allowing charges on premium credit cards, alongside separate debit and credit fees and mandatory least-cost routing to help reduce payment costs.
This request was ignored.
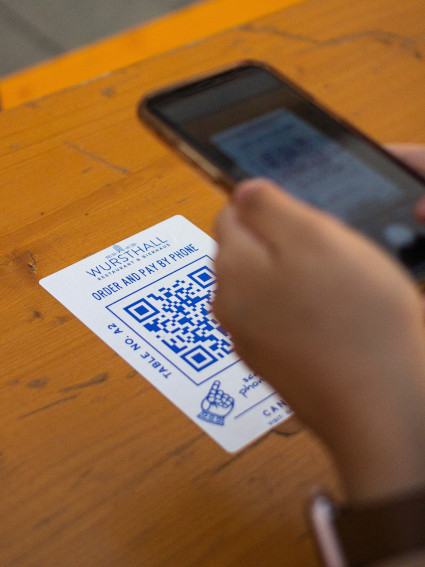
The impact extends beyond traditional EFTPOS terminals. QR code ordering platforms, increasingly common in pubs, clubs and hospitality venues, are also changing how customers are charged.
Platforms including me&u have introduced new platform fees for customers ordering through their systems. Under me&u’s updated fee structure, a 60-cent fee applies to orders between $25 and $49.99, although venues can choose whether to absorb the charge or pass it on.
For an individual patron, the additional cost may be relatively small. Across hundreds or thousands of transactions, however, payment and ordering fees can become a significant expense for venues operating on tight margins.
The Australian Competition and Consumer Commission has confirmed that genuine fees for services such as ordering and booking platforms are not automatically prohibited by the surcharge changes. However, businesses must not mislead customers about prices, the purpose of additional fees or whether charges are optional.
For publicans and club managers, understanding the full cost of payment arrangements is becoming increasingly important. Reviewing merchant statements, comparing payment providers and examining alternative payment options could help identify opportunities to reduce expenses.
Cash discounts are another option. The Reserve Bank and ACCC have confirmed that businesses can offer discounts for cash or other payment methods, provided these are clearly disclosed before customers commit to a purchase.
Some venues may choose to absorb processing costs to protect the customer experience. Others may increase menu prices, encourage cash payments or reconsider the payment methods they accept.
The reforms also raise questions about the role of banks and payment networks, which continue to collect fees while hospitality businesses manage the practical consequences. Reducing interchange fees does not necessarily mean lower overall payment costs if other charges increase.
For pubs and clubs, the central issue is that removing a surcharge does not eliminate the expense. It simply shifts the cost into menu prices, operating margins or new digital ordering fees.
The Government has presented the changes as cost-of-living relief. Whether patrons genuinely benefit without placing further pressure on hospitality operators remains to be seen.
In the meantime, venues will need to scrutinise payment costs, review pricing and make informed decisions about how transactions are handled. The challenge is to protect already-tight margins without making a visit to the local pub or club more expensive for customers.
The AHA National CEO Stephen Ferguson advised hoteliers to use the AHA comparison tool to compare banks and other payment service providers, but reminded operators that price was not the only factor in decision making.
“Talk to your current provider – ask what they can offer and, if you’re considering switching, give them the opportunity to compete.”